Observed listing prices, activity and data quality.
This is a selected snapshot, not a live feed.
Market evidence — how recently we observed the venue: 30m ago (last observation 2026-10-19T19:05:15.227Z).
Venue data age at capture — how old the venue’s own figures already were at that moment: 5m. This is a lag measured in the past, not time elapsed since.
Intelligence — when these derived figures were computed from that evidence: 25m ago (computed 2026-10-19T19:10:40.971Z), published 2026-10-19T19:22:00.427Z. The three can fail independently: collection can stop while the venue feed is healthy, and computation can stop while both are current.
Scope ended 1,542.44s ago · Method listing-features-v3 · Read 2026-10-19T19:35:42.435Z
Snapshot 9916beb208a7760e3829ed5a2f574268506365bc2168acbd18f5b494f694c29d · selected by the active snapshot pointer
FloatAlpha Market Pulse · Minimum listing price basis. Based on 149 of 149 tracked assets with a 1h comparison. This describes FloatAlpha’s tracked research universe on Skinport, not the whole CS2 market.
No asset matches the selected screen.
Most Active ≥ 12.5/100 over 1h; Quiet Markets ≤ 0.3472/100 over 24h. Listings Contracting/Expanding use at least 2% change over the selected horizon. Fresh Changes require a nonzero minimum-price or listing-count change over one step, an observation no more than 90m old, and a venue feed no more than 900s behind when it was read. Movers sort absolute return; Up/Down select its sign. High Volatility is EXPERIMENTAL: it ranks complete-horizon log-return standard deviations, which on low-priced assets are dominated by the one-cent tick. It assigns no trading classification.
These thresholds are calibrated from the frozen seven-day dataset and are provisional. Most Active uses p95 of 1h activity over the frozen dataset; Quiet Markets uses p25 of 24h activity over the frozen dataset. Both must be re-evaluated at the 30-day cutoff.
Activity counts minimum-price and listing transitions over complete five-minute pairs. Minimum listing price is the cheapest observed listing; median listing price describes the broader book. Both are reported, and neither replaces the other. Returns are listing prices, not executed trades. Unchanged observations remain valid.
Price rising + listings contracting and Price falling + listings expanding are descriptive market states, not signals. A large part of the inverse relationship between the cheapest listing and listing count is a mechanical property of an order-book snapshot, and no predictive value is established.
| Asset | Listings | Listings Δ / 1h |
|---|
No available observations qualify.
Venue listing quantity, not circulating supply.
| Asset | Minimum · USD | Activity / 1h |
|---|---|---|
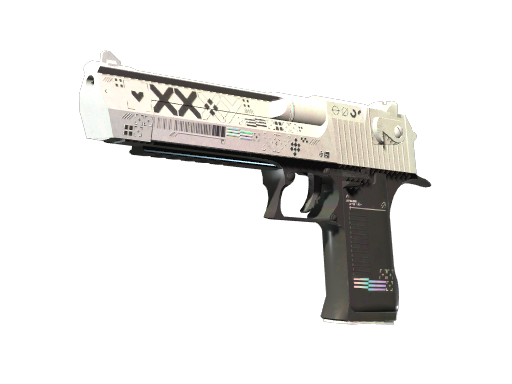
| Desert Eagle | Printstream (Field-Tested) | 32.56 | 25 |
3 more market movements are available with a free account, along with the complete screener, saved watchlists, condition alerts and your CS2 inventory valuation.
Pro access is included during early access. No card required.